German machine tool orders rose by 14 percent in the first half of 2026, supported by demand from aviation, defence and other growth sectors. Production continued to decline, however, and industry association VDW cautions that a broad recovery has yet to take hold.
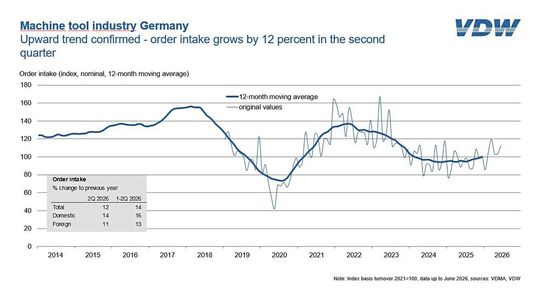
The positive trends experienced in the machine tool industry are continuing into the second quarter: incoming orders increased by 12 percent compared to the previous year.
(Source: VDW)
The recovery of the German machine tool industry is taking shape. In the second quarter of 2026, incoming orders were up 12 percent compared to the same period of the previous year. After a rise of 15 percent in the first quarter, the first six months have seen an overall growth of 14 percent. Domestic orders increased by 16 percent and orders from abroad by 13 percent.
“Two quarters in a row with a double-digit order increase is an encouraging sign. The slump is behind us and we’re now on course for better times,” says Bernhard Geis, Head of Economics and Statistics at VDW (German Machine Tool Builders’ Association), commenting on the figures. “However, it’s too early to give the all-clear. The baseline was low and project business is still making a considerable contribution to growth. There are only limited grounds for talk of a widespread recovery of demand.”
Aviation and Defense driving demand
The development continues to vary considerably according to customer industry. Aviation and Defense appear particularly dynamic. There is also plenty of demand from the electronics industry and medical technology. The situation remains more difficult in metal processing and mechanical engineering, while the biggest challenges continue to be found in the automotive and supplier industry. Here, the share of total sales for the German machine tool industry dropped to 23 percent in 2025. The largest customer sector remains mechanical engineering with 27 percent. The aviation industry, on the other hand, has increased significantly: its share rose by five percentage points to reach 11 percent within a period of two years.
Improved order situation has not yet reached production
This recovery has not yet reached production. In the second quarter, calculations estimated a 6 percent drop on the previous year. In the first six months, production declined by a total of 7 percent to around 5.9 billion Euro. However, the improved order situation should make more of an impact over the remaining course of the year.
There are also signs of stabilization when it comes to export activities. In the second quarter, exports were still four percent lower than the previous year. A far slower decline when compared to the first quarter. As the largest market, the US remains a key pillar of the industry. Deliveries to the US increased by 8 percent in the first six months. In contrast, exports to the second biggest market, namely China, fell by 24 percent. However, companies have recently reported signs of stabilization and a slight revival of Chinese demand. In view of the intense price competition, the principle of “Local for Local” continues to be a key mantra for German manufacturers with their own on-site production facilities.
In Europe, German machine tool industry exports fell by a total of 6 percent in the first six months of the year. France saw positive developments with a plus of 25 percent and a return to its position as the third most important sales market. Positive developments were also seen in Poland and the Czech Republic. India stayed on course for continued growth and has since become the fourth largest market of the industry.
Domestic orders increasing
Domestic development remains strained, however, with domestic sales 10 percent below the figure for the previous year in the first six months. And yet there are positive signs coming from the increase in domestic orders. Economic indicators such as the ifo Business Climate Index and the Purchasing Managers’ Index are also currently documenting a better industry outlook. With a drop of two percent, imports held up better than domestic sales. Japanese and South Korean manufacturers, in particular, were able to increase their sales in Germany. Overall, domestic consumption fell by 6 percent, demonstrating that sluggish investment on the German market has not yet been resolved.
Capacity utilization has recently stabilized at around 75 percent. At the same time, the process of structural adjustment in the industry continues. Around 60,000 people were employed by companies in June, representing a good 6 percent less than the year before. Production figures are now currently around a third lower than the peak phases of earlier years. Bernhard Geis sums it up: “Total order intake has been heading in the right direction for six months now. It is crucial that this leads to a sustainable recovery.”
Date: 08.12.2025
Naturally, we always handle your personal data responsibly. Any personal data we receive from you is processed in accordance with applicable data protection legislation. For detailed information please see our privacy policy.
Consent to the use of data for promotional purposes
I hereby consent to Vogel Communications Group GmbH & Co. KG, Max-Planck-Str. 7-9, 97082 Würzburg including any affiliated companies according to §§ 15 et seq. AktG (hereafter: Vogel Communications Group) using my e-mail address to send editorial newsletters. A list of all affiliated companies can be found here
Newsletter content may include all products and services of any companies mentioned above, including for example specialist journals and books, events and fairs as well as event-related products and services, print and digital media offers and services such as additional (editorial) newsletters, raffles, lead campaigns, market research both online and offline, specialist webportals and e-learning offers. In case my personal telephone number has also been collected, it may be used for offers of aforementioned products, for services of the companies mentioned above, and market research purposes.
Additionally, my consent also includes the processing of my email address and telephone number for data matching for marketing purposes with select advertising partners such as LinkedIn, Google, and Meta. For this, Vogel Communications Group may transmit said data in hashed form to the advertising partners who then use said data to determine whether I am also a member of the mentioned advertising partner portals. Vogel Communications Group uses this feature for the purposes of re-targeting (up-selling, cross-selling, and customer loyalty), generating so-called look-alike audiences for acquisition of new customers, and as basis for exclusion for on-going advertising campaigns. Further information can be found in section “data matching for marketing purposes”.
In case I access protected data on Internet portals of Vogel Communications Group including any affiliated companies according to §§ 15 et seq. AktG, I need to provide further data in order to register for the access to such content. In return for this free access to editorial content, my data may be used in accordance with this consent for the purposes stated here. This does not apply to data matching for marketing purposes.
Right of revocation
I understand that I can revoke my consent at will. My revocation does not change the lawfulness of data processing that was conducted based on my consent leading up to my revocation. One option to declare my revocation is to use the contact form found at https://contact.vogel.de. In case I no longer wish to receive certain newsletters, I have subscribed to, I can also click on the unsubscribe link included at the end of a newsletter. Further information regarding my right of revocation and the implementation of it as well as the consequences of my revocation can be found in the data protection declaration, section editorial newsletter.